


One of the strongest monopoly positions takes another hit. And the stock reacts with a 20% drop.
Fair Isaac $FICO is falling sharply today after another significant change in the US mortgage market. FHFA chief Bill Pulte announced that Fannie Mae and Freddie Mac will move to a single common pricing system, in which VantageScore 4.0 will be placed alongside Classic FICO.
Why is this important?
Just a few weeks ago, VantageScore was disadvantaged in mortgage pricing. To get into the same pricing band as with a FICO score of 780+, a client needed a VantageScore of 800+. In practice, there was a 20-point handicap that reduced the motivation of mortgage companies to switch to the competition.
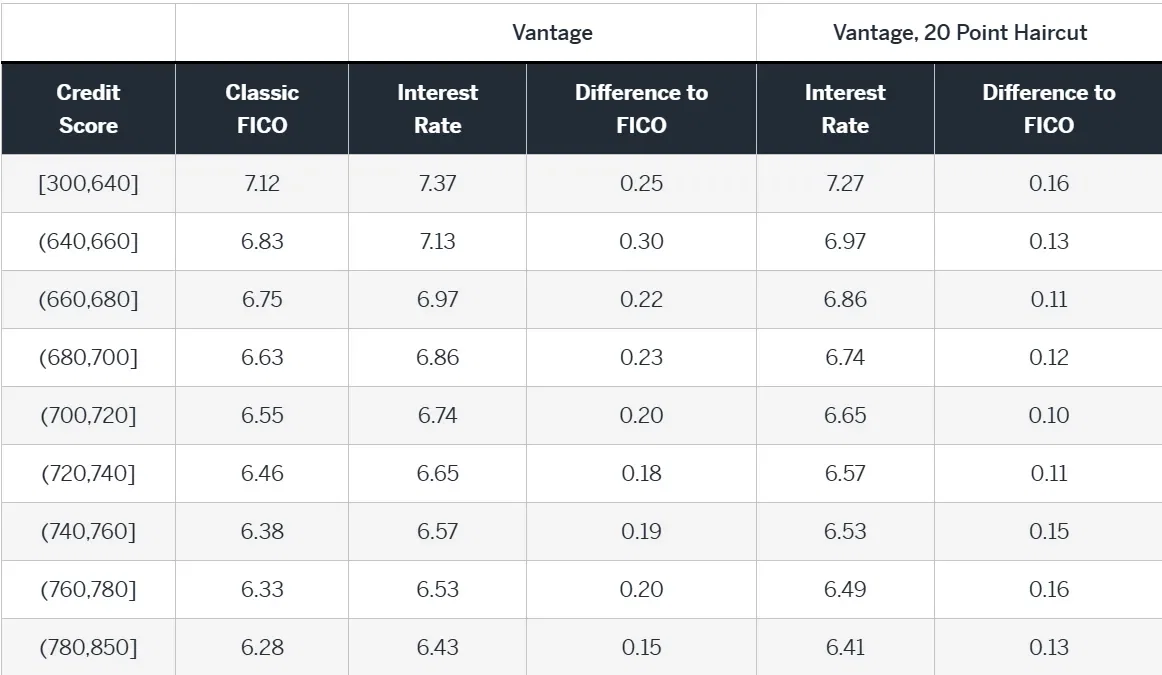
Data from the pilot phase also showed that even after accounting for the 20-point adjustment, rates for VantageScore in individual score bands were about 10 to 20 basis points higher than for FICO.
The new unified system is intended to remove this 20-point disadvantage. However, Fannie Mae and Freddie Mac have not yet released exact technical details or an effective date. So I would not yet claim that the new system definitively sets the highest VantageScore band at 780+. But the direction of change is clear... VantageScore is to get more comparable terms with Classic FICO.
And that's not all. Rocket Mortgage announced that starting in Q4 it will use VantageScore as the preferred model for all mortgages where this model is allowed. This is important because it is no longer just about the possibility of using the competition. One of the largest mortgage providers is starting to use it as the default choice.
For FICO this is a problem mainly because of the economics of the Scores segment. In the last quarter it brought in $459 million out of total revenues of $674 million and achieved an incredible 91% operating margin. The company also said that 49% growth in B2B scoring revenues was driven mainly by higher prices for mortgage credit scores. So the market is not reacting only to the risk of volume decline. It is mainly reassessing the pricing power that was one of the most valuable qualities of FICO's entire business.
One more important note on prices. VantageScore is available through Experian for $0.99 per mortgage score, while Classic FICO has a price of $10 per score for the classic model. However, it is not a completely 1:1 comparison, because FICO also offers an alternative direct licensing model for $4.95 per score plus a fee at loan funding.
How do I see it?
$FICO will probably not lose its business overnight. It has decades of built-up position, many integrations, and moreover is not dependent only on mortgages. Its credit scores are also used for credit cards, cars, and personal loans.
But its investment story is changing from "a practically mandatory product with extreme pricing power" to "a dominant product that for the first time has to really compete on volume and price." And that could mean a lower multiple until we see how much market VantageScore actually takes.
I would mainly watch the share of new mortgages sold to Fannie Mae and Freddie Mac where VantageScore starts to be used. That will tell us much more than today's nearly 20% drop itself.
Do you have $FICO shares in your portfolio?
