Next Week's Game Plan 🎯
🗓️US Macro Calendar Next Week (October 5, 2026) – Key Events for Market🗓️
➡️Monday: S&P Global Services PMI (Sep), ISM Non-Manufacturing PMI (Sep).
➡️Tuesday: ADP Employment Change Weekly.
➡️Wednesday: FOMC Meeting Minutes
➡️Thursday: Initial Jobless Claims
➡️Friday: Michigan Consumer Expectations / Sentiment (Oct), Michigan Inflation Expectations (Oct)
🔹Monday: Services are most of the US economy. A reading above 50 means expansion. ISM is the one markets trade; the employment and prices sub-indexes matter more than the headline after Friday’s weak jobs print.
🔹Tuesday: A look at August imports and exports. It feeds the GDP math, but it rarely moves markets on its own.
🔹Wednesday: These are the notes from the September 15–16 meeting, when the Fed hiked to 3.75–4.00%. They show how split the committee was on another hike. They do not include Friday’s soft payrolls.
🔹Thursday: The weekly layoff count. It is the high-frequency labor pulse, not a full jobs report.
🔹Friday: A household survey of confidence and of where people think prices are going. The inflation-expectations line is what the Fed watches.
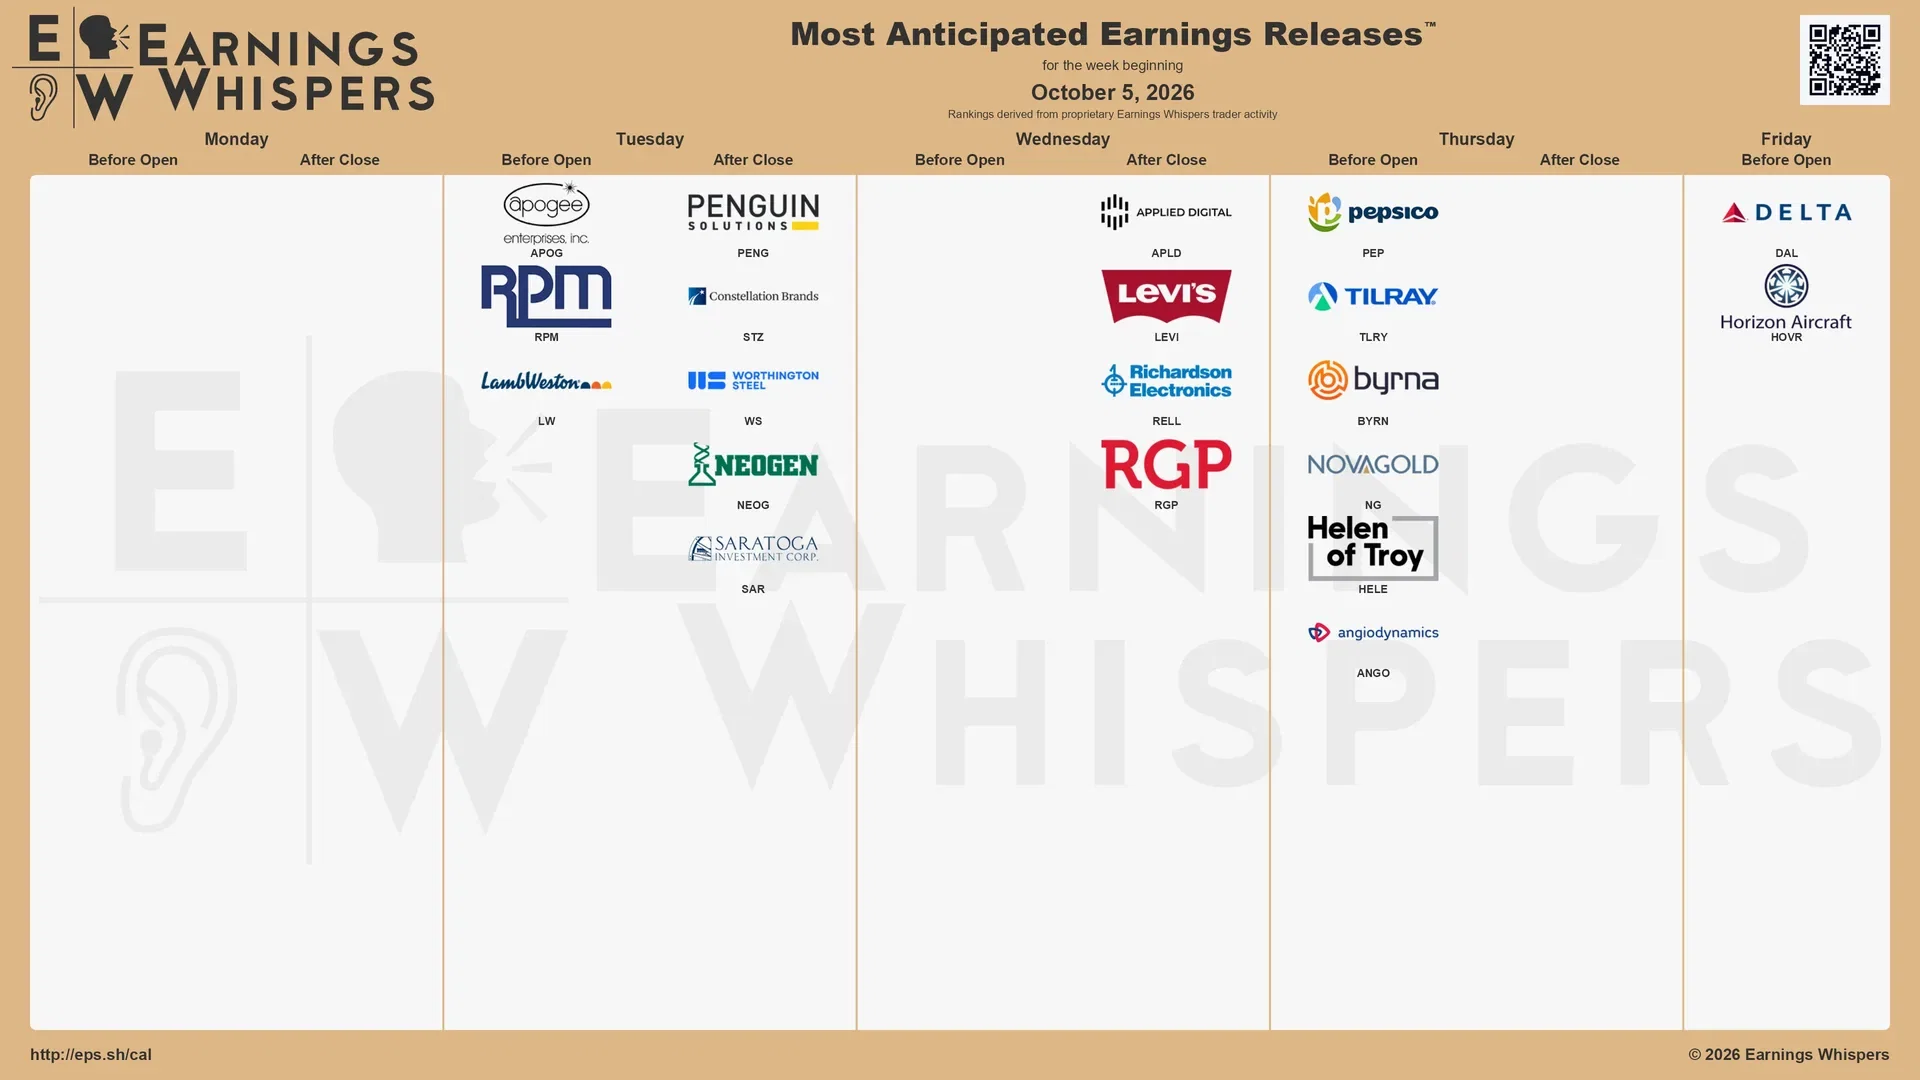
🚨Most Anticipated Earnings Next Week (October 5, 2026)🚨
➡️ Monday: -
➡️ Tuesday: $APOG (Apogee Enterprises), $RPM (RPM), $LW (Lamb Weston), $PENG (Penguin Solutions), $STZ (Constellation Brands), $WS (Worthington Steel), $NEOG (Neogen), $SAR (Saratoga Investment Corp.).
➡️ $APLD (Applied Digital), $LEVI (Levi’s), $RELL (Richardson Electronics), $RGP (RGP).
➡️ $PEP (PepsiCo), $TLRY (Tilray), $BYRN (Byrna), $NG (NovaGold), $HELE (Helen of Troy), $ANGO (AngioDynamics).
➡️ Friday: $DAL (Delta), $HOVR (Horizon Aircraft)
◆ 🥤 Staples, brands and the consumer wallet — PEP, STZ, LW, LEVI, HELE:
PepsiCo is the volume-versus-price read: organic volume in beverages and Frito-Lay, elasticities after two years of price, and whether North America snacking is still holding or trading down. Constellation Brands is the beer-demand check — Modelo and Corona depletions, shipment versus depletion gaps, and wine-and-spirits drag show whether Hispanic and mainstream drinkers are still paying up. Lamb Weston is the foodservice pulse: frozen-potato volumes, quick-service restaurant traffic, and contract pricing track real restaurant demand, not grocery headlines. Levi’s is the apparel-and-inventory read — wholesale versus DTC mix, full-price sell-through, and Europe/Americas commentary show whether denim is clearing or still being discounted. Helen of Troy is the housewares check: Hydro Flask, OXO and Osprey sell-in, retailer destocking, and gross margin show whether home and outdoor brands are still moving off the shelf.
◆ 🖥️ AI infrastructure and data-center buildout — APLD, PENG:
Applied Digital is the data-center capacity read: energized megawatts, hyperscaler and HPC lease signings, and power-interconnect timing show whether AI hosting demand is still being contracted or slipping. Penguin Solutions is the memory-and-systems check — AI server integration, specialty DRAM/high-bandwidth supply, and solutions backlog show whether the buildout is still pulling hardware, not just narrative.
◆ ✈️ Travel and discretionary demand — DAL:
Delta is the premium-travel check: domestic versus transatlantic yields, corporate booking curves, and capacity plans show whether higher-income flyers and managed travel are still holding into the fall.
Which events are you watching closer next week? Write down in the comments! 👇
#StockMarket #Investing #FinancialMarkets #Macro #EarningsSeason