


Well, $PEP results are out. Let's get into it👇
PepsiCo is growing everywhere except at home
🟢Net revenue rose by 5.6%, or 6.7%, respectively.
🟢Organic revenue rose by 3.1%, or 2.7%, respectively.
🟢Earnings per share (EPS) rose by 17%, or 47%, respectively.
🟢Core EPS rose by 2%, or 5%, respectively.
🟢Core constant currency EPS rose by 1.5%, or 2%, respectively.
At first glance, the third quarter looks very good for $PEP. But then you open the segment table and it's not so rosy...
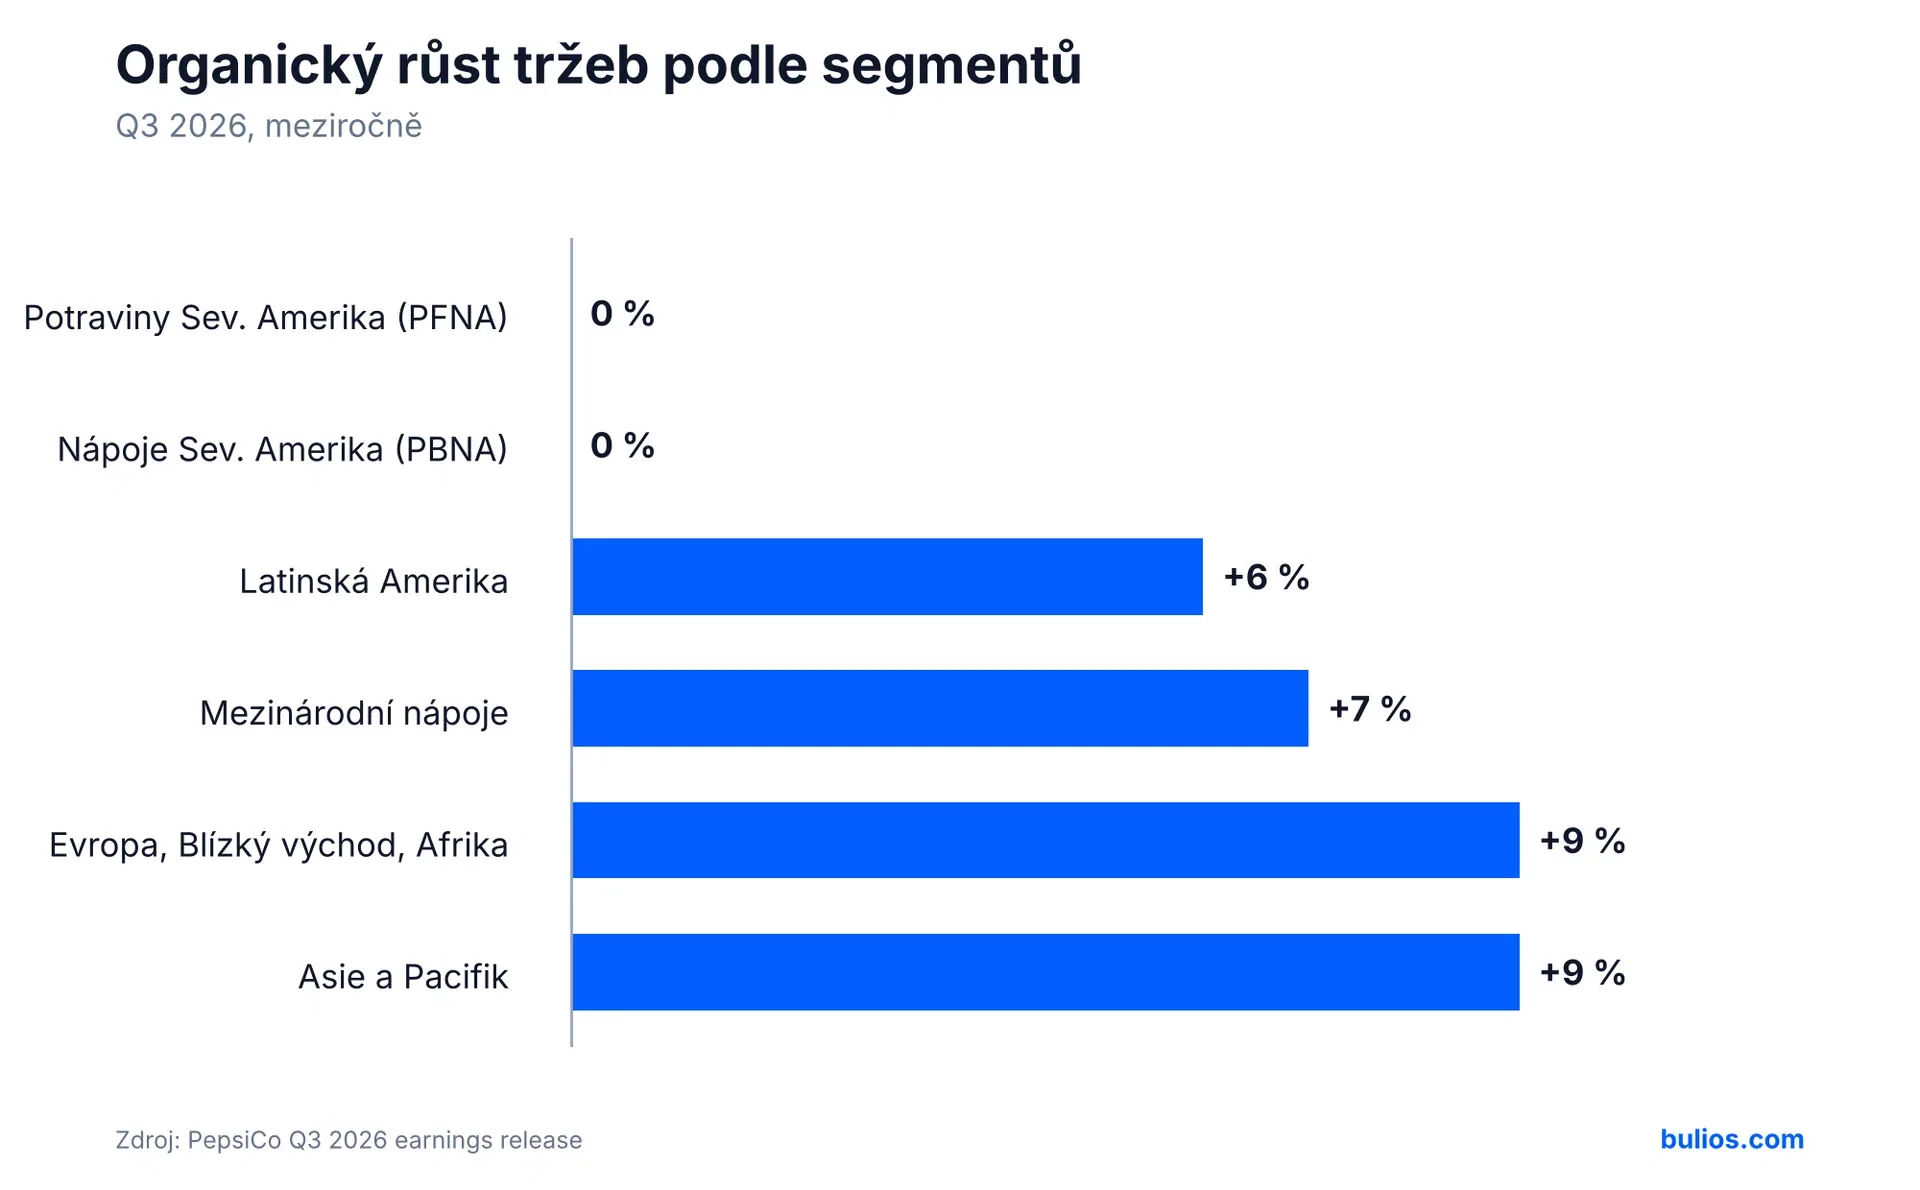
North America, which accounts for more than half of the company's total revenue, didn't grow organically even by a percent. Oh, and management also lowered the earnings guidance for the second time in a row.
Business diversification is working against the company
We all probably know that Pepsi, compared to Coke $KO, is involved not only in the beverage segment, but also in the "food, snack" segment, whatever you want to call it :)
The food division in North America (Lay's, Doritos, Cheetos, and Quaker) has exactly 0% organic revenue growth, and its operating profit fell by 12%. The company is selling more individual packages and gaining market share, but it has to cut prices to do so.
Beverages in North America posted revenue growth of 5%, but almost all of it came from acquisitions in 2025. Organically, the segment is flat, and volumes fell by 2%.
Meanwhile, the international business is on a completely different track. Asia and Pacific grew organically by 9%, with snack volumes up 11%. The Europe, Middle East and Africa region added 9%, international beverages 7%, and Latin America 6%. Core operating profit in Latin America rose by 20%, in the EMEA region by 16%, and in Asia by 14%.
Reported EPS of $2.23 (+17%) looks great, but much of it is due to one-off items and a comparison with last year burdened by impairments.
More important is core EPS of $2.34, i.e., growth of just 2%. Core operating margin decreased by 35 basis points to 16.9%, even though the company was helped by tariff refunds amounting to roughly 4 percentage points of operating profit growth. Without them, operating profit would have roughly stagnated.
However, cash flow is positive. Operating cash flow for the first 36 weeks rose from $5.5 billion to $8 billion, and investments fell to $2.2 billion.
Guidance goes down for the second time
PepsiCo lowered its guidance for core EPS growth this year to +2.5% to 3.5%, whereas previously it had spoken of the lower end of the +5% to 7% range. In constant currency, that's only +1% to 2%. The company reduced organic revenue growth guidance to roughly 3%.
🔴When I first opened the report, the headline numbers that the company nicely put right at the top looked great. I saw that the stock was up almost 2%. By the time I got to writing, I saw that the stock is in the red. Probably more investors got to that guidance...
The CEO talks about the need to act in North America with urgency and announced further structural cost cuts to fund investments in innovation and marketing while also offsetting rising input costs. In other words, margins will not be a priority in the coming quarters.
Dividend remains an anchor
For dividend investors, nothing changes. The company will return $8.9 billion to shareholders this year, of which $7.9 billion in dividends. The quarterly dividend of $1.48 gives a yield of over 4% at the current price around $135, which is historically above average for $PEP.
So, are you satisfied with the results?