


What if new data on a company that has lost nearly 65% of its value show the exact opposite of what the market fears? 👀
The latest report from Tenjin revealed some very interesting figures on AppLovin $APP . In Q3 2026, the company captured 53% of iOS mobile gaming ad revenue, up from 44% in Q2. On Android, its share rose from 23% to 29%, even surpassing Google AdMob (22%).
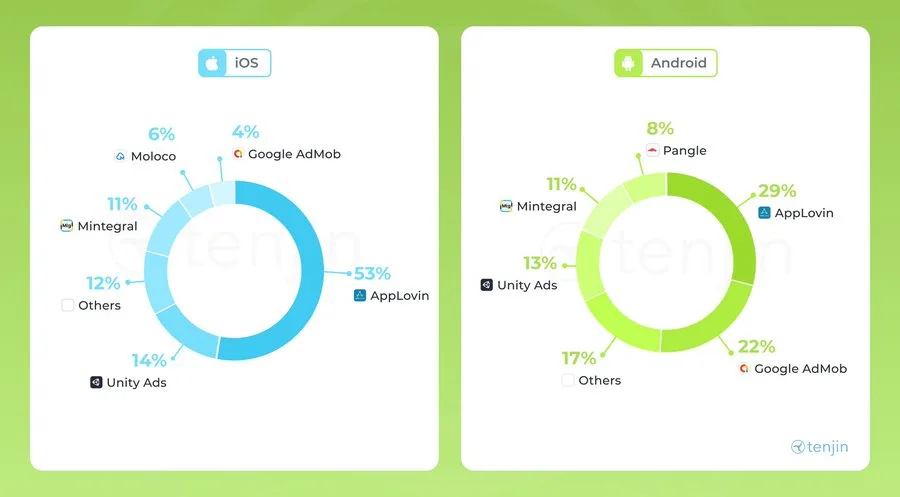
This isn’t a share of the entire mobile advertising market, but rather gaming ad revenue tracked by Tenjin. Even so, the trend is quite clear: year over year, AppLovin gained 11 percentage points on iOS and 10 on Android.
It’s not just about how much market share it’s gaining, but why
This could be further evidence of the technological edge of its Axon AI advertising system. If it can deliver better returns for advertisers, they’re willing to pay more for ads. Game developers then earn more, AppLovin wins more ad auctions and gains additional data to improve its models.
This could create a very strong competitive advantage that won’t be easy to replicate. And the numbers are already showing this mechanism at work. In Q2, AppLovin’s revenue grew 53% to $1.92 billion, while net advertising revenue per install rose 58%, even though the number of installs itself fell by 2%.
This is very important. The company isn’t growing just because of a higher volume of advertising, but mainly because it can monetize the existing volume more effectively. And because this is a highly profitable software model, improved performance has the potential to translate significantly into earnings and cash flow.
And how much can we buy this business for today?
After its massive plunge, the shares are trading around $260, at a P/E of about 20, a forward P/E of 14.4 and a P/FCF of around 19.
For a company whose revenue most recently grew 53%, I think those are very interesting multiples. But the market is also discounting real risks: uncertainty about the pace of further Axon improvements, competition, legal disputes and whether the company can successfully expand beyond mobile gaming.
And the pace of Axon’s improvement is one of the biggest question marks today. In Q2, new model improvements arrived later than management expected, contributing to investor disappointment. CEO Adam Foroughi, however, said they were deployed early in Q3 and were delivering better results.
Now we’re seeing AppLovin gain further share on both platforms in Q3. This doesn’t prove that the models’ performance has improved in any way, but it certainly doesn’t support the idea that its competitive edge is disappearing, either.
And I see a potential catalyst here, too. The next earnings report is due as soon as November 4, and analysts expect revenue of about $2.08 billion. If the new Axon improvements have translated into higher absolute revenue and earnings, AppLovin could surprise positively again.
Of course, Tenjin’s reported share gains alone don’t guarantee revenue growth or a beat against estimates. But combined with what management has communicated, I think this is a pretty interesting signal.
Personally, I feel the market is punishing AppLovin today mainly because of uncertainty about future growth, while its competitive position remains quite strong. And at the current valuation, the potential return-to-risk ratio is starting to make more and more sense to me.