


$COIN: $719M PROFIT, BUT WE’RE SEEING SELLOFFS IN THE MARKET. WHY?
📊 HOW IS THE COMPANY AND MY POSITION DOING?
$COIN makes up approximately 1.7% of my portfolio. My average purchase price is $151.6, and the position is currently down −6.1% (price: $142.4 during trading on 30. 10. 2026).
The stock is down more than 11% after the results, from yesterday’s close of $160.59. At first glance, the quarter looks excellent. But when I look beneath the surface, I understand why the market reacted coolly.
✅ WHAT’S GOING ON? (THE NUMBERS)
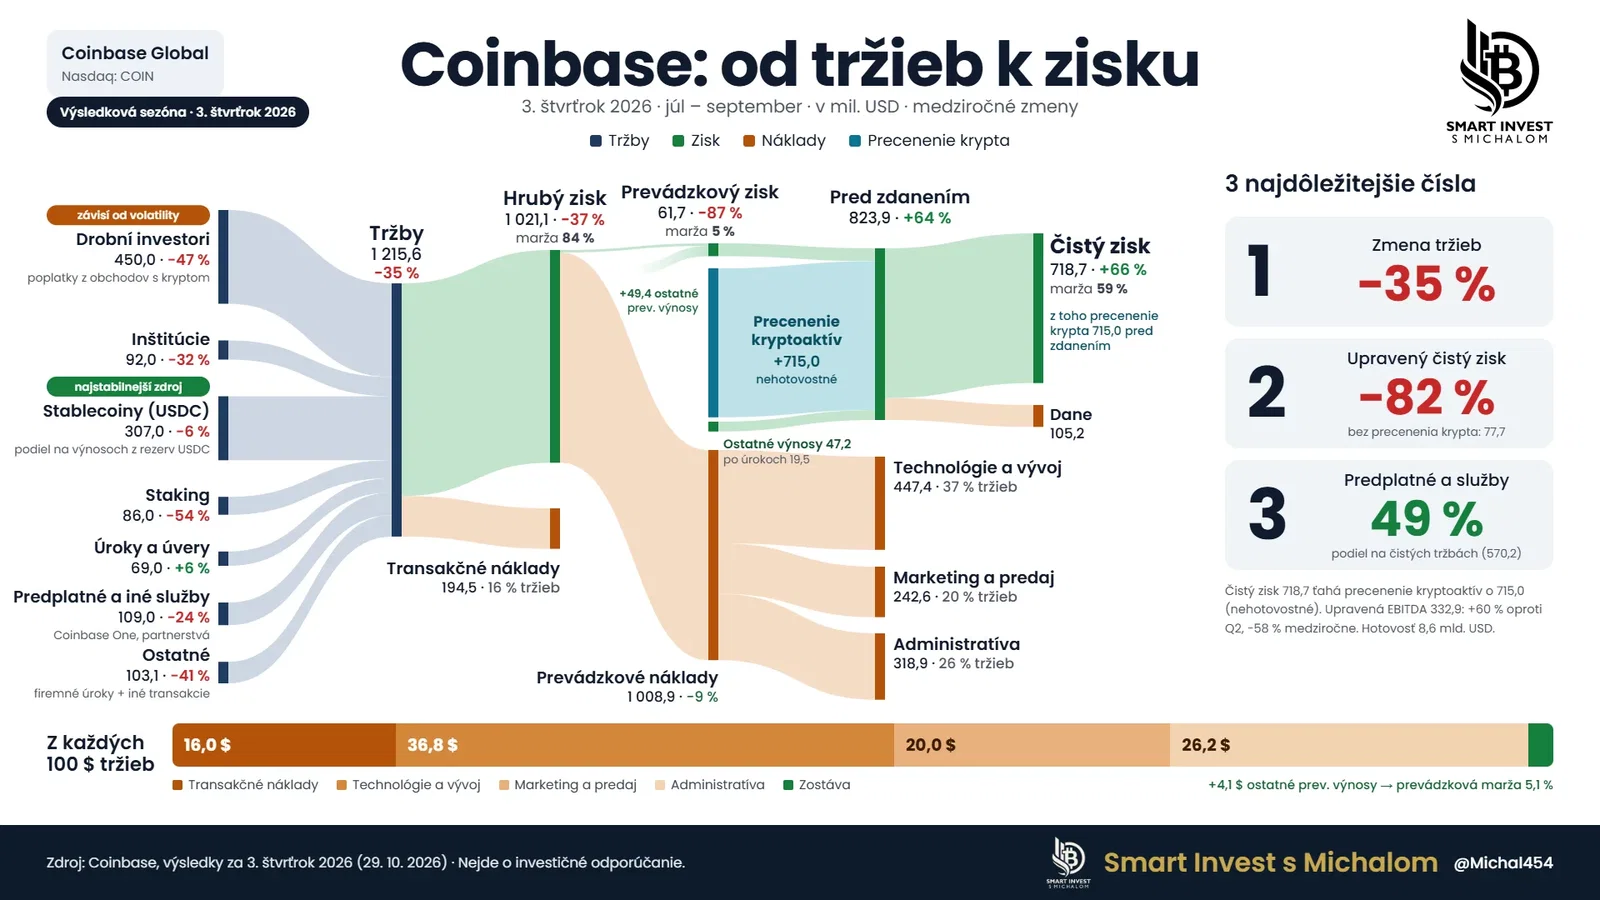
❌ Revenue of $1.216B, down −35% year over year and unchanged from Q2. The consensus ranged from $1.20B to $1.233B (LSEG via CNBC $1.233B; Seeking Alpha $1.22B; MarketBeat $1.21B; 28.–29. 10.). Generally in line, slightly below LSEG.
✅ Diluted earnings per share of $2.51 versus an expected loss of $0.10 to $0.23 (Benzinga, MarketBeat). However, nearly all the profit came from a $715M revaluation of crypto assets. This is a non-cash item that can reverse when crypto prices fall.
❌ Adjusted net income of $77.7M, down −82% year over year. Analysts expected around $112M, according to Bloomberg (cited by Startup Fortune).
✅ Adjusted EBITDA of $333M, up +60% from Q2 and down −58% year over year. The fifteenth consecutive profitable quarter.
📉 Transaction revenue of $590M (−44%). Retail investors: $450M (−47%); institutions: $92M (−32%). Crypto volatility was at multi-year lows, according to the company.
💰 Subscription and services revenue of $570M (−20% year over year, +3% from Q2), representing 49% of net revenue. Guidance was $500M to $580M. Stablecoins contributed $307M, with average USDC held in Coinbase products at a record $22B.
📊 Operating margin of 5.1% versus 25.7% a year ago. Adjusted expenses of $975M were below the $980M to $1.080B outlook ✅
📈 Q4 outlook: subscription and services revenue of $550M to $630M. Transaction revenue for October through 25. 10. was approximately $165M. Full-year adjusted expenses were lowered again to $4.15B to $4.30B.
🧠 WHAT IS MANAGEMENT SAYING?
Fact: The company has $8.6B in cash. Since the start of the year, it has repaid $1.27B of debt and repurchased $1.25B of its own shares. It has $2B remaining for further buybacks. The share count fell from 267.8M to 264.8M. So the buybacks aren’t being funded with new debt, but the balance sheet still carries $5.9B in long-term debt.
Fact: The company has 4,204 employees, compared with 4,795 a year ago. The May layoffs are now showing up in costs.
Plan: The merger of the INTX and Deribit derivatives exchanges is complete, and Coinbase Pro returns in Q4. Prediction markets have an annual revenue run rate above $200M. Armstrong wants to spend more time on customers and products in 2027.
Tone: Armstrong says new products are already bearing fruit, but the market hasn’t seen it yet. CFO Haas also cautions against drawing conclusions from October’s numbers.
Analysts’ questions were brief and conducted via X. They focused on Bitcoin (the company has now bought its 18,000th BTC), its relationship with Circle, and AI agents. The answers weren’t evasive, but neither were they specific. There weren’t many figures shared about the return of retail trading.
🔍 MY TAKE
Diversification is working, but for now it’s only acting as a buffer. Subscription and services are keeping revenue around $570M, and prediction markets are growing. But the core business still depends on volatility. October comes to approximately $6.6M in transaction revenue per day, compared with $6.4M in Q3. That’s not a significant recovery yet.
I also see risk in stablecoins. Their yield depends on interest rates, so a decline would hit the most stable part of revenue.
Valuation: At a price of $142, the market cap is around $37.7B. That’s about 6.7 times revenue for the last 4 quarters ($5.63B) and 27 times adjusted EBITDA ($1.41B). That’s not cheap for a company with revenue down −35%.
My strategy with $COIN is simple. I treat the stock as a bet on Bitcoin’s halving cycle. Whenever the price reaches support around $145 to $146, I buy at least one share. That’s how I bought this dip too. I plan to sell the vast majority of my position when the halving cycle peaks.
In my view, weak trading and low volatility are typical of a phase when it makes sense to accumulate. The numbers also confirm cost discipline, so the company is getting through this period without balance-sheet problems.
I see a risk in the fact that the price fell below my support today, to $142. If it stays below that level, the support no longer holds and a lower test could follow.
📌 SUMMARY
* The $719M profit was driven by crypto revaluation; adjusted profit fell 82%.
* Revenue is down −35%; trading is held back by low volatility.
* Subscription and services (49% of revenue) and prediction markets are stabilizing the company.
* Expenses came in below guidance, the balance sheet is strong, and buybacks are funded without new debt.
* I’m buying at support around $145 to $146; I’ll sell most of my position at the peak of the halving cycle.
With $COIN, I’m reminded once again that profit on paper and cash from the business are two different things. If you’re interested in how I manage positions like this across my portfolio, you can follow or copy me on eToro.
This is not investment advice. I’m sharing my approach.