$PANW: Revenue +39% and a raised outlook. But who will pay for the new $4.5B bet on artificial intelligence?

📊 HOW THE COMPANY IS DOING AND MY POSITION
Palo Alto Networks makes up approximately 3.1% of my portfolio. My average purchase price is $169.53, and the position is currently up roughly +118% (the share price after the results was around $370). It is one of my most successful positions, so what interests me most is whether the numbers still justify such a high valuation.
✅ WHAT'S GOING ON?
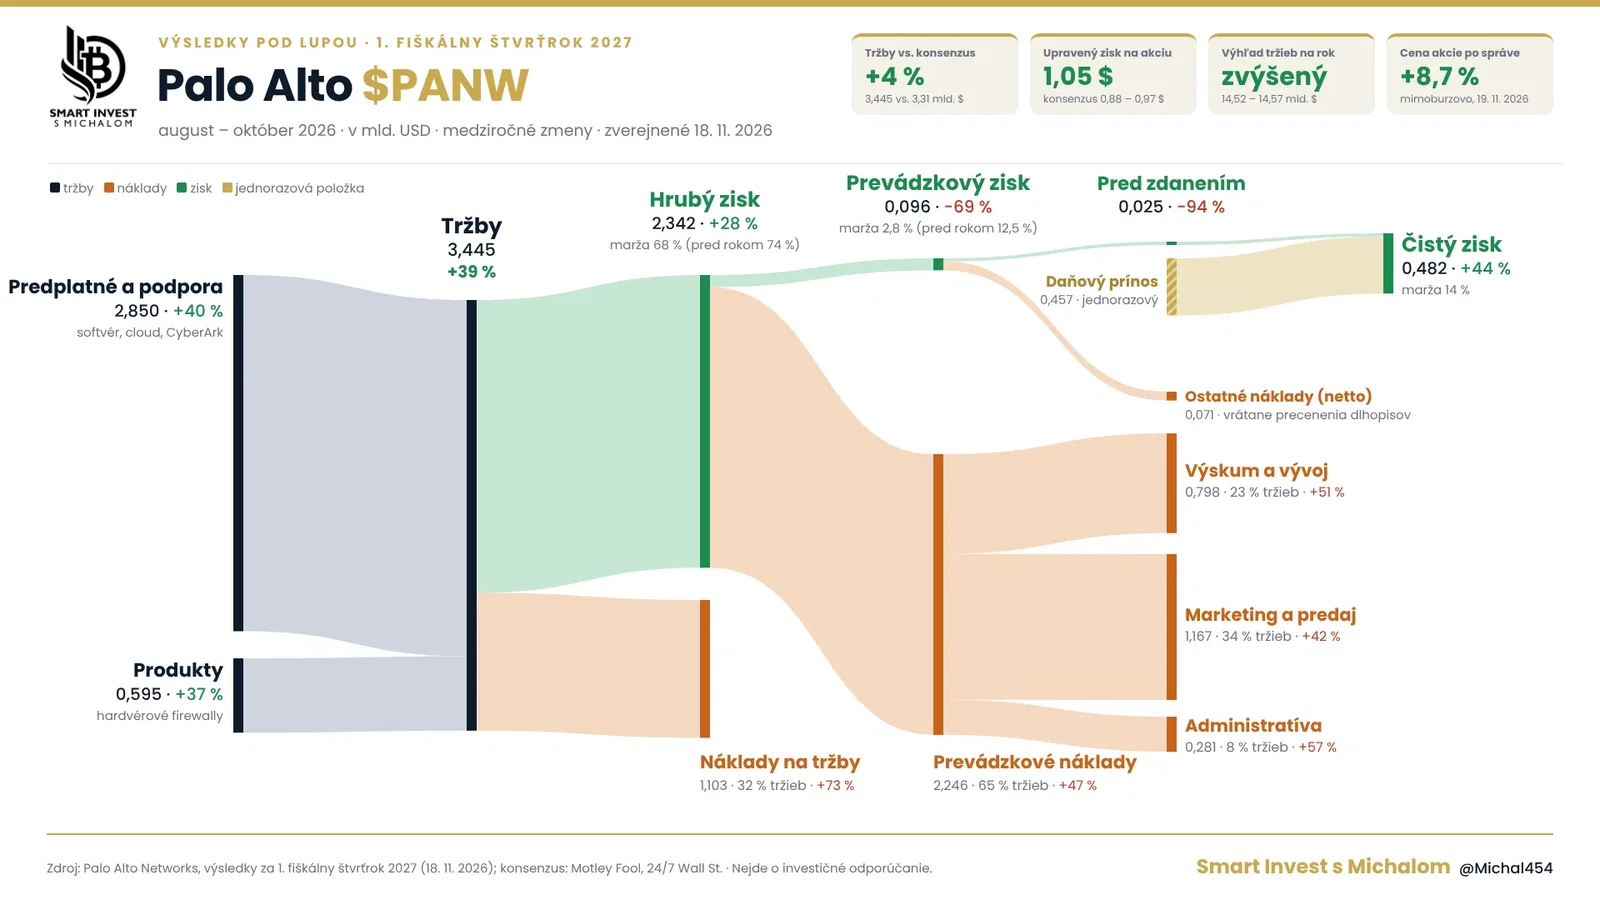
✅ Revenue reached $3.445B, up +39% year over year. Analysts expected $3.31B, so the company beat their estimate by approximately 4%. The catch: growth is being boosted significantly by the acquisition of CyberArk, and the company did not disclose organic growth. The network security and AI security segment, which was unaffected by the acquisition, grew by 20%.
✅ Adjusted earnings per share were $1.05 (+13%), while consensus was $0.97 (some sources reported $0.88). The catch: adjusted net income rose by 33%, but the share count increased by 18%, so shareholders received less of the growth.
❌ GAAP operating income fell by 69% to $96M, and the operating margin is just 2.8% (12.5% a year ago). This is due to amortization of intangible assets from the acquisition ($282M) and stock-based compensation ($622M).
📊 Net income of $482M (+44%) looks good, but it's largely a one-off. Pre-tax income was only $25M, with the rest coming from a $457M tax benefit due to a change in tax position. This won't happen again.
📉 Adjusted gross margin fell to 75.2%, down 1.7 percentage points. The reasons are more expensive components and a higher share of cloud services. Adjusted operating margin, on the other hand, rose to 30.7% (+0.5 percentage points).
💰 Adjusted free cash flow reached $1.94B, with a 56% margin (69% a year ago). The first quarter is seasonally the strongest; for the full year, the company expects a 38% margin.
📈 Next-generation security platform annual recurring revenue (NGS ARR) reached $9.73B (+66%). Remaining performance obligations (RPO) stand at $21.0B (+35%).
✅ The company raised its outlook for the full fiscal year. It expects revenue of $14.52 – $14.57B (previously $14.10 – $14.20B) and adjusted earnings per share of $4.26 – $4.30 (previously $4.16 – $4.19). For the second quarter, it expects revenue of $3.53 – $3.55B (+36 to 37%). I couldn't find full-year analyst consensus in sources I verified.
🧠 WHAT DOES MANAGEMENT SAY?
Palo Alto is buying Applied Compute for $4.5B, entirely in stock. Applied Compute develops a platform for fine-tuning and running open AI models. The transaction is expected to close in the third fiscal quarter.
Management expects the acquisition to generate more than $1B in recurring revenue by fiscal 2029. It also acknowledges that the acquisition will reduce operating margin by 1 percentage point this year and 2 percentage points next year. Investments in computing capacity are expected to total no more than $3B by 2030.
A record 170 new customers moved to the full platform during the quarter. The Prisma AIRS product for AI security now has nearly $170M in recurring revenue.
The company did not repurchase any of its own shares this quarter. However, it approved a new buyback program of up to $1B through the end of 2027. That's approximately 0.3% of market value, and the company will fund it from its own cash, not debt.
Management came across as very confident. It answered questions about demand for firewall appliances directly and admitted that some customers placed orders early, before the price increase. When asked whether its AI ambitions would harm relationships with partners, CEO Nikesh Arora responded more figuratively than concretely. The vision of “fighting AI with AI” sounds compelling, but the numbers to back it up are still missing.
⚠️ WHAT TO WATCH OUT FOR
❌ Shareholder dilution: the share count rose by 18% over the year, and more new shares will go toward the purchase of Applied Compute.
❌ Earnings quality: a one-off tax benefit, not operations themselves, is keeping GAAP earnings positive.
❌ Valuation: at a share price around $370, that's approximately 86 times this year's adjusted earnings outlook and approximately 21 times revenue, according to my calculations. Motley Fool cites 82 times expected earnings at a price of $340.
❌ Gross margin pressure will continue throughout the year, and the company is entering the more capital-intensive computing capacity business.
🔍 MY TAKE
I think demand for cybersecurity is real, and the numbers confirm it: recurring revenue, contracted revenue, and free cash flow are all growing. On this point, management's words match the numbers. They don't match on earnings. Adjusted figures look excellent, while GAAP figures are significantly worse, with the difference driven by acquisitions paid for in stock.
In my view, this is still a high-quality company, but at this price the market is already paying for perfection. I'm holding the position and not selling. I'd consider buying more only at a price around $300 (roughly 70 times the earnings outlook) or once the company demonstrates organic growth above 20% even without the impact of acquisitions.
📌 SUMMARY
1️⃣ Revenue and adjusted earnings beat expectations, and the outlook is higher.
2️⃣ Growth is largely acquired; the company did not disclose organic growth.
3️⃣ Net income was boosted by a one-off $457M tax benefit.
4️⃣ Applied Compute is a big bet on AI that will reduce margins and dilute shareholders over the next two years.
5️⃣ A valuation of more than 80 times earnings leaves little room for error.
With $PANW, I'm reminded once again that a good company and a good price are not the same thing. If you're interested in how I incorporate results like these into my portfolio, feel free to follow me or copy my portfolio.
This is not investment advice; I'm sharing my approach.
Stocks mentioned