


Komerční banka shares have experienced a 45% decline this year. Is this an ideal buying opportunity?

Today, I would like to focus on Komerční banka shares, which have been frequently mentioned recently in connection with buying at a significant discount. KB presented us with its quarterly results in August, which are good and satisfactory beyond measure. So why are KB shares actually falling? Is this a brilliant opportunity for a bargain investment?

Basics and introductions 👇
Komerční banka is a banking institution operating on the Czech capital market majority owned by the French financial group Société Générale. It is a joint stock company and its shares are tradable on the Prague Stock Exchange. Komerční banka provides financial products and services for citizens, entrepreneurs, small and large enterprises and the state administration.
How was KB'squarter ?
Komerční banka's shares continued to dominate in the second quarter of this year. The driving force was none other than rising interest rates.
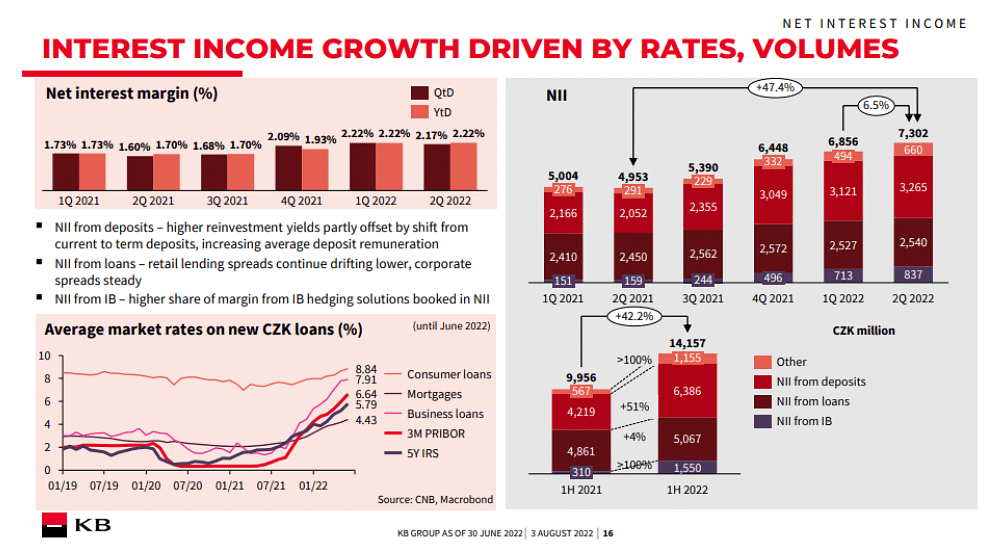
The graphic is taken directly from KB's presentation.
KB reported the following for the quarter:
Net interest income of CZK 7.302 billion (up 47.4% year-on-year).
Net fee and commission income rose to CZK 1.477bn (+4.2% yoy).
Net profit rose to CZK 4.806bn (up 53.6% yoy).
Total operating income increased to CZK 9.690bn (+31.2% yoy).
Earnings per share (EPS) CZK 25.29 (53.6% YoY growth)
As can be seen in the image below 👇
Net interest income grew 47.4% YoY, while we can also see a solid YoY growth in net interest margin from 1.70% to 2.22%.

Operating expenses increased by 4.7%, which is not entirely surprising. However, KB says it is looking to streamline and restructure to prevent further growth in this item. The focus is on streamlining itself, which will mean that it won't need as many staff and will reduce staff costs 👇
No matter how much I look, I couldn't find anything in the financial statement that outright worried me and justified the massive 45% drop in YTD.

As for the dividend, I find it one of the attractive things about KB and it will be paid at 43.8k. And of course, not forgetting the extraordinary dividend from retained earnings from previous years. At the same time, the bank is building up reserves from profits, which only reinforces my view that there should be no surprises about the next payout 👇

Why is KBstock fallinganyway ?
One would expect KB to record at least some growth based on promising results. However, the opposite is true and KB stock has experienced nothing but a series of declines so far. But let's cut to the chase - the uncertainty about the windfall tax has been, and for now still is, behind the unfavorable development of KB's share price, which is very limiting.
Windfall tax = Windfall tax is a higher tax rate on profits that result from a sudden windfall in a particular company or industry, often as a result of geopolitical unrest and war.
Now you may be thinking - Can a tax really restrict society in such a way? While that may sound absurd, it is a harsh reality and it is true.
However, to better specify my thoughts - I view KB very positively and see the current price as a great investment opportunity that is also spiced with an interesting dividend. The political problems and the associated Windfall tax is a very speculative topic that would merit an article in itself, but today I am focusing specifically on KB, which has plummeted to a very attractive price based on these uncertainties (no wonder many investors have decided to open a position). KB is a strong, stable, and judging by next quarter's results, successful bank that should definitely not be overlooked at this point. I think all the uncertainties about the sector tax are already priced in and I don't expect another drastic fall (but you know how it is, one politician says the wrong thing and it's off to the races). On a risk:reward basis, I rate KB positively and would not be at all worried about a relatively quick future comeback and erasing this loss.
Outlook and price predictions

Komerční banka expects more than 20% growth in operating income, supported by net interest income.
The cost of risk is expected to be around 30 bps.
KB's loan portfolio is also expected to grow positively. This should be driven by another positive quarter in corporate and mortgage lending.
The analysts covering KB see this as very positive over the next 12 months and as you can see in the figure, the average estimate is 896p and at best up to 1,085p.
Are you investing in KB stock?
Do you expect them to recover from the declines fairly quickly?
And of course, let me know your opinion on the sector tax that is holding down a few Czech stocks despite promising results.
Please note that this is not financial advice. Every investment must undergo a thorough analysis.




