


Why I wouldn't buy Nvidia stock despite a 60% drop from all-time highs

Nvidia shares plunged nearly 15% last week, hitting a new local low after the company disclosed that the US government ordered restrictions on shipments of a select portfolio of high-margin chips to China. The announcement comes after Nvidia had already warned of slowing demand for its gaming products.

Problems are mounting
In my opinion, Nvidia $NVDA stock is overvalued over the long term, as evidenced by its average P/E ratio over the past 5 years of nearly 58 . And although NVDA stock is down about 60% from its all-time highs late last year, I would venture to say that there is still some excessive valuation premium that needs to be corrected in order for investors to enjoy an attractive risk-reward ratio.
In the last quarter, Nvidia provided an outlook that was much lower than analysts expected. The chipmaker has faced a number of challenges in recent months, including declining demand for its gaming and professional visualization products, macroeconomic cost pressures and supply chain disruptions.
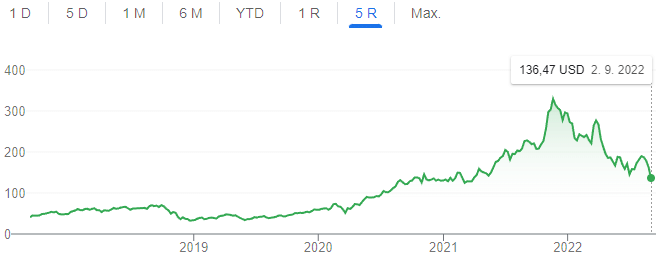
Five-year price chart of NVDA stock
US government restricts chip sales to China
The U.S. government made a $400 million hole in Nvidia's budget last week. The semiconductor company said Wednesday that federal officials informed it last Friday that they had imposed new export controls that prevent Nvidia from selling its latest data center chips in China or Russia without a license.
While Nvidia doesn't sell its products to customers in Russia, China and Hong Kong generated $1.6 billion in sales in the quarter ended July 31. The government's ban on selling its latest chips could cost it an estimated $400 million, and that's just for this quarter. The long-term impact of the restrictions is not yet known.
Nvidia will therefore have to struggle to sell its less advanced chips in China, with it unclear to what extent the company will be able to convince its Chinese customers to accept its less advanced chips as a replacement.
Still a very high valuation
Even though Nvidia's stock is down nearly 60% from its all-time highs, its valuation is still very expensive. Investors should consider that the 2023 earnings multiple for Nvidia is now nearly 38x, more than double the sector premium. That the stock is expensive is also indicated by a price-to-earnings (P/B) ratio of 11.45, which implies a premium of up to 300% over the sector. Given the slowing economic cycle in the semiconductor sector and declining investor confidence in US growth stocks, these multiples are quite high.
Paying too much for an investment can be very dangerous. Analysts estimate that average annual revenue growth from 2023-2027 will be 11.19%. That's a significant slowdown from the previous period, when sales grew by an average of nearly 26. At a slightly faster rate than sales, analysts say the company's profitability should grow, averaging 12.82%. But it should decline from that over the next year.
Conclusion
Nvidia is undoubtedly a great company that specializes in gaming and data center products. Although I am bullish about the company's long-term prospects, I believe NVDA stock has further to fall before its price becomes attractive enough.
Personally, I wouldn't buy NVDA stock at a valuation above 30 P/E, which are still very high multiples. Accordingly, I would need to see another drop of a few dozen percent before the risk/reward becomes legitimately attractive and to sufficiently reflect regulatory risk and the slowing business cycle.
DISCLAIMER: All information provided here is for informational purposes only and is in no way an investment recommendation. Always do your own analysis.
Stocks mentioned




