


These 4 stocks have the potential to increase the value of your money by up to 200% over the next 10 years

In order to triple the money over 10 years, our average annual rate of return would have to be 11.5%. Here are 4 companies that have growth and dividend yield prospects and that can deliver the returns needed to triple an investor's money over the next decade.

Enbridge, which owns and operates pipelines across Canada and the United States
NextEra Energy $NEE
One of the seemingly unstoppable dividend aristocrats that also has significant growth potential is NextEra Energy. This clean energy-focused company expects its dividend to continue to grow at a healthy pace over the next few years, thanks to its investments in renewable energy.

NEE stock has added over 93% over the past 5 years
As an energy company, NextEra Energy generates very stable earnings that are supported by a state-regulated rate structure and long-term contracts. Meanwhile, demand for electricity and natural gas tends to be relatively stable even during recessions. This provides the company with a stable income that supports its payout. NextEra also has an excellent balance sheet with an A rating that is supported by solid credit metrics. This gives it better access to low-cost financing to invest in expansion projects.
Overall, NEE gets a unanimously strong buy from Wall Street based on 10 positive ratings. The stock trades at $72.75 with an average price target of $99.30, suggesting a 36.49% gain over the next 12 months. (See NEE stock forecast on TipRanks)
Enbridge $ENB
Headquartered in Calgary, Canada,Enbridge operates as an energy infrastructure company. The company has five segments - Liquids Pipelines, Gas Transmission and Midstream, Gas Distribution and Storage, Renewable Energy Generation, and Energy Services. Enbridge is one of the best dividend yielding companies with a dividend yield of 7.26% as of October 13.
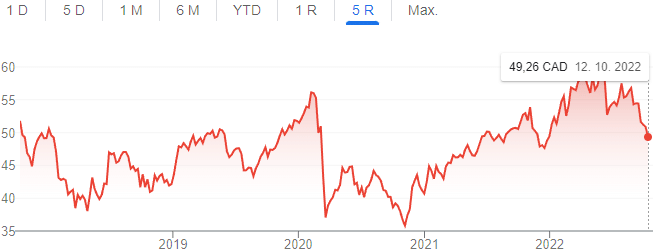
ENB shares are trading almost the same as they did 5 years ago
One of the most interesting things about Enbridge's energy business is that it generally avoids the ups and downs of commodity prices. That's because it charges for the use of its midstream and pipeline assets. It is a reliable business that is driven by energy demand, which remains strong even as the world slowly shifts to cleaner alternatives
On September 29, Enbridge announced the acquisition of US renewable energy firm Tri Global Energy for $270 million in cash and assumed debt. The acquisition will strengthen Enbridge's renewable energy platform while supporting its growth strategy in North America.
Overall, ENB gets a strong buy from Wall Street based on 7 positive ratings. The stock trades at $35.62 and has an average price target of 43.20, suggesting a 21.28% gain over the next 12 months. (See TipRanks' forecast for ENB stock)
Prologis $PLD
Prologis is an American real estate investment trust company based in California. It is one of the largest industrial real estate companies in the world. Prologis currently pays a quarterly dividend of $0.79 per share with a dividend yield of 3.14% as of October 13. The company holds an eight-year history of dividend growth and ranks among the top dividend stocks in the REIT sector.
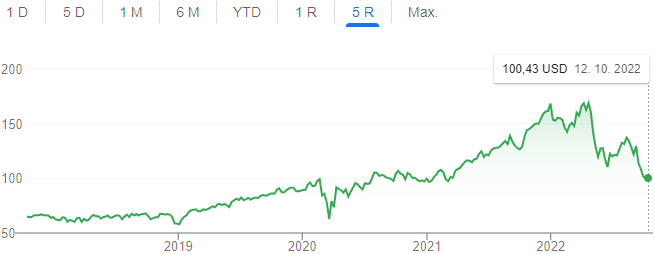
PLD shares have appreciated by more than half over the past five years
Prologis has several significant acquisitions in the works, including the purchase of Duke Realty, which will almost immediately increase its funds from operations (FFO). But that's not the only thing going for it. Over the next five years, 56% of the company's leases will expire, giving the REIT a huge opportunity to boost net operating income. Even if the robust rent growth the company is experiencing today slows dramatically, it still means about $2 billion in increased rental income.
Overall, PLD gets a unanimously strong buy from Wall Street based on 13 positive reviews. The stock trades at $100.43 with an average price target of $149.92, suggesting a 49.28% gain over the next 12 months. (See PLD stock forecast on TipRanks)
Brookfield Infrastructure $BIP
Last is Brookfield Infrastructure, one of the world's largest owners and operators of critical infrastructure networks, including capabilities in data movement and storage, energy, freight and water, and passenger transportation. Among other things, the company boasts a more than 13-year history of paying dividends. The yield currently stands at 4.34%.
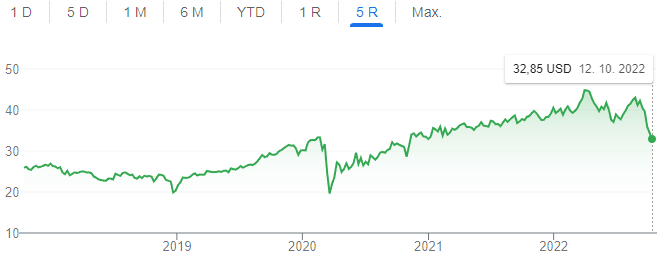
BIP stock has added more than a quarter of its value over the past 5 years
The company is defensive, doing business in core areas that tend to be recession-proof; has a solid business base in which it can set prices and pass them on to customers, making it inflation-proof; and has growth potential because infrastructure is a common way politicians spend money. Brookfield achieves excellent results through its network of more than 2,000 global infrastructure investments in more than 30 countries. The company's businesses include renewable energy, real estate and private equity, among others.
Overall, BIP receives a unanimously strong buy rating from Wall Street based on 6 positive reviews. The stock trades at $35.98 with an average price target of $46.17, suggesting a 28% gain over the next 12 months. (See TipRanks' forecast for BIP stock)
DISCLAIMER: All information provided here is for informational purposes only and is in no way an investment recommendation. Always do your own analysis.




