Intel jumped 85% in a month. Is foundry euphoria the beginning of a new era, or overblown FOMO?

Intel shares have roughly doubled in value over the past month, an extreme move for a "heavy" blue-chip semiconductor company in such a short time. The reason is not the classic PC business, but the soaring hope that Intel will finally break through with its foundry strategy and win big external customers - most notably Apple and South Korea's SK hynix. So the notion that Intel could become much more than just a maker of its own CPUs: a potential alternative to TSMC in contract manufacturing of high-end chips has seeped into market expectations in a matter of weeks.
But at the same time, analysts warn that much of that euphoria is already priced in. After such rapid growth, Intel is more of a bet on being able to foundry transformation perfectly "off" without major mistakes than a cheap ticket to a hypothetical turnaround.
What started the 85% growth
The impetus came mainly from the media. A series of reports - from major titles to Korean sources - described Intel's foundry division $INTC as being in talks for specific contracts with Apple $AAPL and SK hynix. The very fact that there is any serious talk at all of Apple putting some of its M-series chips in Intel's hands is a major shift: just a few years ago, Apple was almost synonymous with TSMC $TSM in high-end manufacturing.
For investors, this means two things at once. First, that Intel has clearly managed to get its manufacturing processes to a level where large customers are willing to consider diversifying outside of TSMC. Second, that the foundry story is no longer a purely internal "promise for the future" but is starting to take the shape of sales and concrete contracts. It is no coincidence that 85% of the rally took place against the backdrop of this change in perception.
As Deutsche Bank sees it: a higher target, but no mindless euphoria
Deutsche Bank responded by raising Intel's target price to $100 per share, but left the rating at "Hold". Translated: fundamentals have improved, models are already pricing in a foundry contribution, but this is no longer a clearly cheap stock after the latest rise.
The bank is working with a long-term earnings power band of around $4-5 per share, to which it is applying a roughly 20 times earnings multiple. Importantly, foundry no longer plays a significant role in these estimates:
Around 2027, they project external foundry revenues of roughly $2 billion
in 2028 about $4 billion
and with the foundry segment tipping into break-even at the operational level just at the end of 2027
From an EPS perspective, this means their 2027-2028 estimates are about 10% above consensus - so slightly more optimistic than the Wall Street average. But not enough to make sense to aggressively push a "Buy" recommendation after an 85% rally.
What an Apple deal would mean in numbers
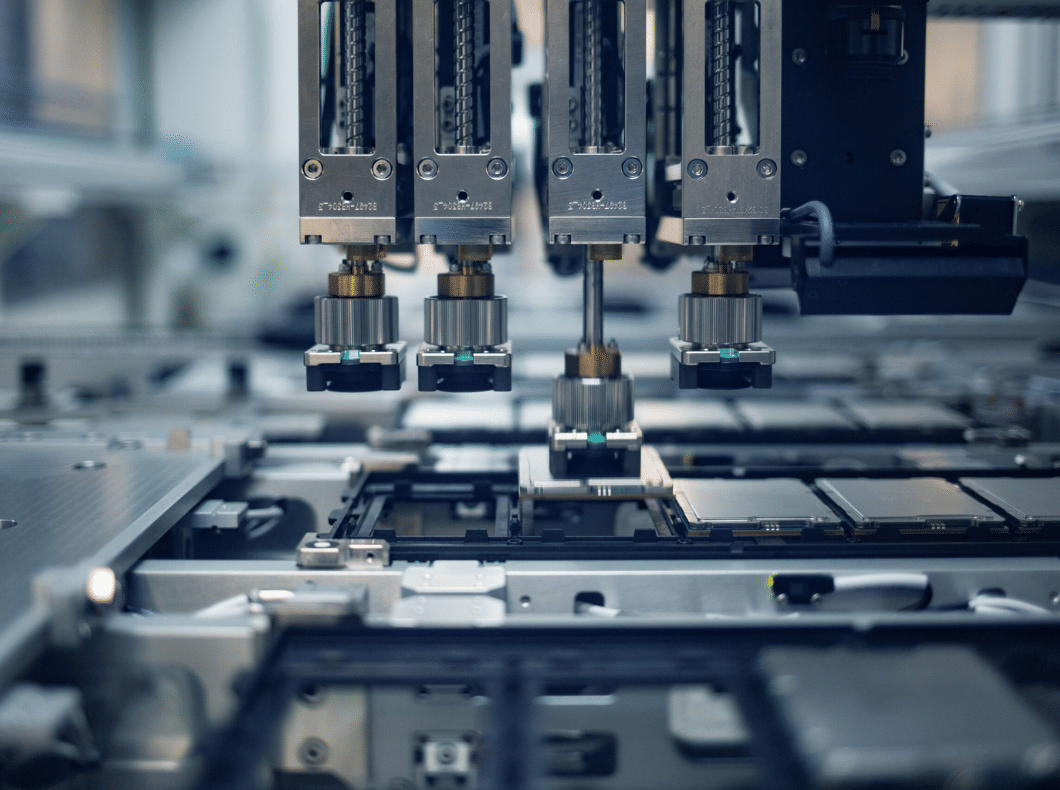
At the center of the speculation is Apple. Rough analyst models suggest that if Intel were to acquire production of just a portion of Apple's M-series chips, its foundry business could cash in on about $2 billion in revenue a year. The figure alone sounds tempting, but the structure is more important: it's front-end wafer manufacturing and advanced packaging, the part of the chain that is most capital-intensive but also the most indicative of a manufacturer's technology level.
At the same time, we must not read the 2 billion as a "net profit bonus". In reality, it comes into play:
pricing (Apple has long been pushing suppliers to the margins)
production yield (every percentage of scrap production burns)
spreading huge investments in factories over a larger number of orders
That's why even Deutsche Bank warns that even if Apple manages to win the contract, it will take years to get the foundry business out of the investment phase and into stable "revenue mode."
Foundry roadmap: revenue, break-even and what's already priced in
Putting together the outlook of $2-4 billion in external foundry revenue in a few years and the idea of a break-even by the end of 2027, a relatively conservative plan emerges. It's not a sci-fi idea of tens of billions over two years, but rather a gradual but realistic path to making the foundry segment start to earn its keep.
But after an 85% rally, the market is already largely accepting this scenario as a baseline. Intel is no longer a "CPU dinosaur that might someday do something in foundry" but a company that investors are implicitly counting on:
get at least one large external customer
handle the ramp-up of production processes without major disruptions
and maintain a disciplined enough capex to make the ROI make sense
In other words: the room for pleasant surprises has shrunk; the room for pain from unexpected delays and technical problems has increased.