SpaceX goes public: 6 things you need to know before buying

The SpaceX IPO prospectus is over 270 pages long and anything but boring. It opens up a detailed look into the finances of the world's most charged private company, connected to AI, data centres and the social web, while showing just how extremely personal a project this is for Elon Musk. The documentary combines grand visions like "a million people on Mars" with very mundane facts like billion-dollar losses and massive investments in AI infrastructure.
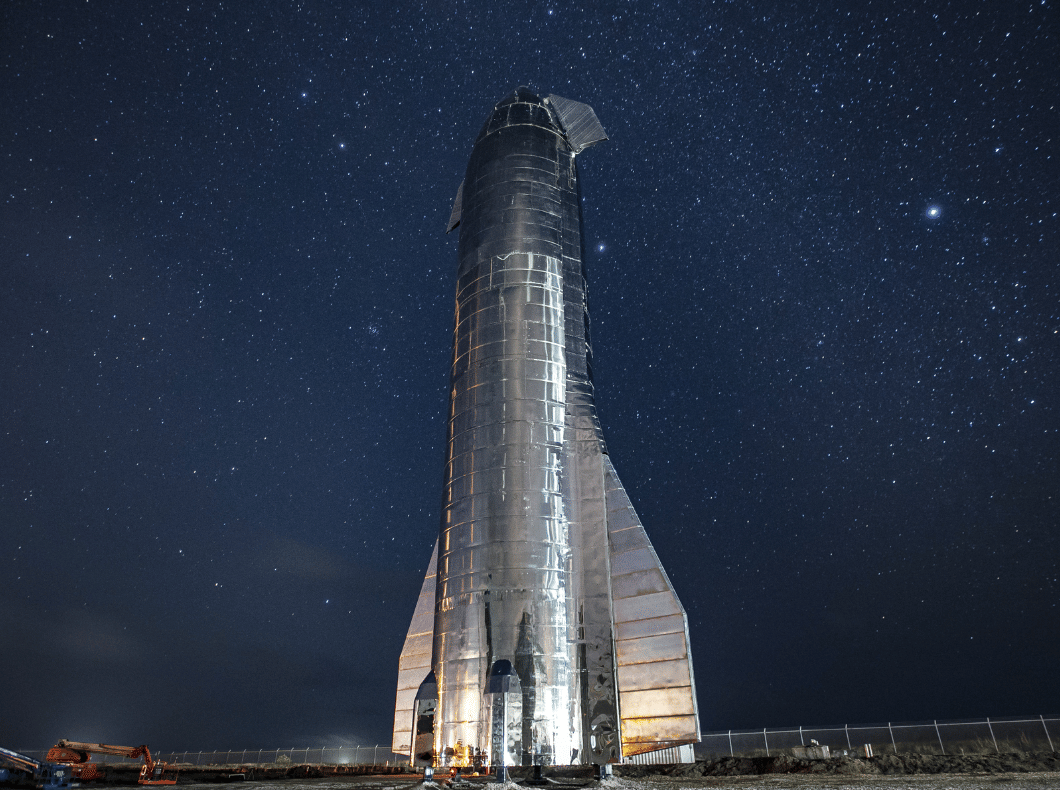
To make sense of it all, I break it down below in six simple blocks: Mars as a reward condition, Musk's practical unwinnability, Tesla's surprise purchases, the financial reality of a huge loss, the nature of the whole project as a grand experiment, and finally the dependence on government
1. Mars as a KPI: a billion-dollar reward conditional on colonization
The prospectus confirms that Musk's ambitions are officially reflected directly in the reward structure. The word 'Mars' appears more than sixty times in the document, including in the section on executive compensation. There are two conditions for the grant of 1 billion restricted shares:
achieving a market capitalization of $7.5 trillion
the establishment of a permanent human colony on Mars with at least one million inhabitants
That's in a whole different league from traditional plans tied to earnings per share or index performance. In practice, it says two things:
SpaceX is defined as a long-term "civilization" bet, not a conventional industrial company
For smaller shareholders, this means that their goals (multi-year returns) and Musk's goals (interplanetary civilization) may not always overlap 100%
2. Musk as an "unprofitable" CEO
The prospectus also shows that Musk has set up his management at SpaceX so that he doesn't have to face the shareholder pressure he saw at Tesla $TSLA. He holds three key roles:
CEO.
CTO
Chairman of the Board
The key is the layering of shares. Musk controls the majority of the voting shares (Class B), giving him approximately 85 per cent of the voting rights. This means:
he can elect and remove board members himself
in practice, he controls all major decisions, including the election of the entire board, mergers, new share issues, changes to the articles of association
From an investment perspective, there are two opposing sides to this:
stability of vision and quick decision-making without "politics" among shareholders
minimal protection for minorities: if Musk decides to take an extremely risky step, investors have no way to stop him
3. Cybertruck and Megapacks: how SpaceX is buying from Tesla
The prospectus reveals in detail for the first time the scope of the transactions between SpaceX and Tesla. In 2024 and 2025:
SpaceX spends nearly $700 million on Tesla Megapack battery storage
plus around $131 million for Cybertruck pickup trucks
So-called "related party transactions" are not uncommon for conglomerates, but two things are interesting here:
Cybertruck is otherwise a weak product for Tesla with complicated sales, but here it found an "in-house" buyer
Estimates based on average prices show that SpaceX could have purchased roughly 1,200 to 1,800 Cybertrucks, which is units of a percent to nearly a tenth of the model's total annual sales
To an investor, this is a signal that Musk's companies operate partly as an in-house ecosystem:
It can make technological sense (Megapacks for bases, datacenters, ramps)
but it also increases the risk that capital will sometimes be allocated according to "group" logic, not purely according to one firm's optimization
4. Financial reality: fast growing revenues, even faster growing losses
The biggest surprise for many readers is the harsh financial reality:
SpaceX made approximately $18.7 billion in the last year
but at the same time ended up with a loss approaching $5 billion.
in the first quarter of the following year, it added more than 4 billion in losses
Key reason: the integration of Musk's AI firm xAI and massive investment in "Colossus" data centers in Tennessee.
The AI division reported roughly 3.2 billion in revenue
but a loss of about $6.4 billion
Capital expenditures were roughly $12.7 billion, more than triple the CAPEX of the rocket division alone
Simply put, SpaceX is less like "just" a rocket company in the numbers and more like an investment vehicle for two hugely capital-intensive areas: space transportation and cutting-edge AI infrastructure.
5. The "grand experiment": technologies that don't exist yet
In the "Our Challenges" section, the company openly admits that much of its plans are in the realm of exploration and experimentation:
a plan to deploy "orbital AI computing satellites" - i.e. data centres in orbit - as early as around 2028
the development of a "lunar economy" and the transport of people and cargo to the Moon and Mars
development of systems for human augmentation
The prospectus itself states that:
these are unproven technologies
some of them do not exist today
the projects may never reach commercial viability
At the same time, the document declares its belief that "the next paradigm shift for humanity is the creation of a resilient, permanently expanding space civilization". At the level of style, this is close to a manifesto; at the level of investment, it's a reminder that you're buying a company that burns some of its capital in the very distant future.
6. Dependence on government procurement and regulation
The prospectus and available information show that a significant part of SpaceX's business is based on its relationship with the state, especially the US government and agencies like NASA and the Pentagon. These include contracts for satellite launches, manned missions to the ISS, human lunar return programmes and military and intelligence contracts. These revenues are long-term but dependent on political priorities, budgets and the company's relationship with the government.
Added to this is the rapidly growing importance of Starlink and the potential future use of satellite internet and space infrastructure for defence purposes. This increases SpaceX's strategic value, but also increases the level of regulation and geopolitical risk. From an investor's perspective, this is another layer to watch:
how contracts with NASA and the military are evolving
what conditions and constraints are imposed by regulators
and how Musk's own appearances or conflicts with politicians may affect the company's relationship with the state
Stocks mentioned