When technology goes down, this stock does very well

While the market got nervous about the possibility of a US interest rate hike today, investors piled into the "boring" stock of a firm that trades soap and diapers. Why are they interested in a company that is gaining significantly today, even as the S&P 500 index is writing off over 2%?
Today's trading day tested the nerves of anyone with a portfolio stuffed with technology. After months of the market being driven forward by a single idea, artificial intelligence, it's sobering. Thanks to repeated positions and FOMU, stocks were very fragile. After today's US labour market report, the odds of an interest rate hike before the end of the year have increased significantly. It is currently around 43%. And that's not good news for tech stocks. Money has started to disappear from these stocks.
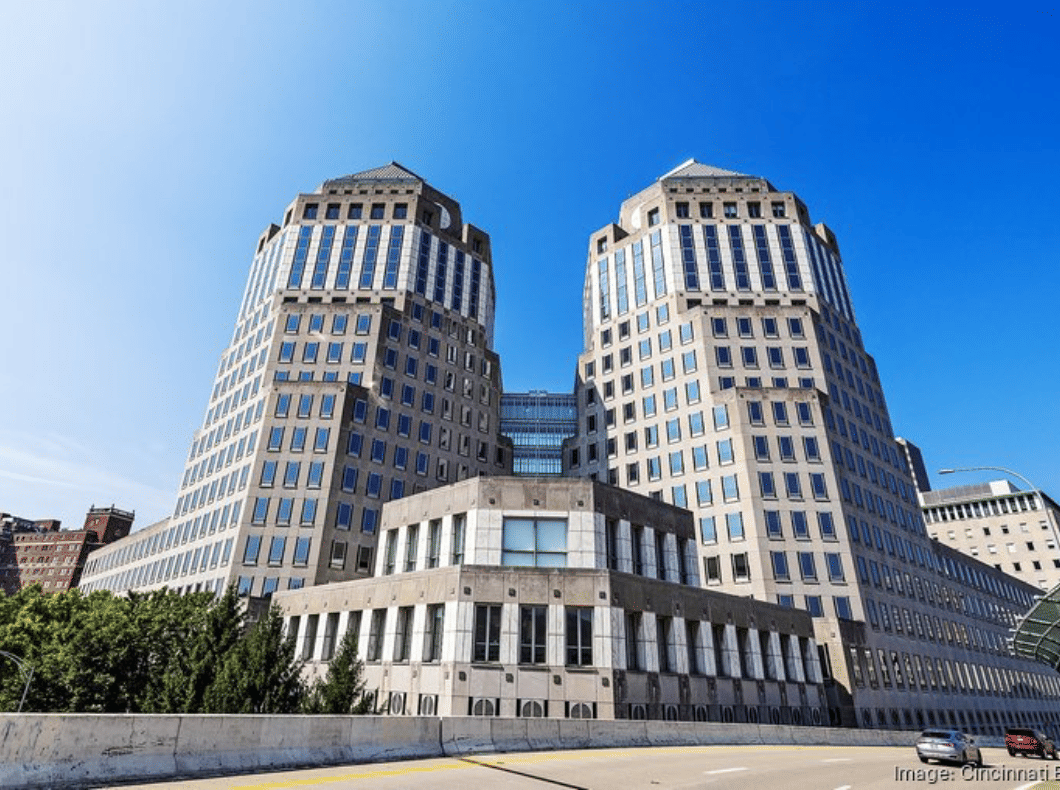
Where has the money gone? Among today's biggest winners is a sector that's so boring it's fascinating: consumer staples. And its most famous and largest representative is Procter & Gamble $PG
Escape to safety
When the future is uncertain, people stop buying new technology, but they keep buying laundry detergent and diapers. This resilience to economic fluctuations is exactly what makes consumer goods manufacturers so-called defensive stocks.
The Consumer Staples Select Sector SPDR $XLP fund, which tracks this very sector, has gained 0.65%. The tech-heavy Nasdaq weakened nearly 5% today.
"Skepticism toward technology investments is pushing capital out of expensive growth stocks. That plays to the defensive trade's advantage."
The results confirm a comeback
A defensive component is nice, but it wouldn't be enough without results. But the company didn't let investors down and delivered very solid numbers in the most recent quarter.
Revenue grew 7% to $21.2 billion and organic growth was 3%. Volume sold added 2%. For the first time in a full year, volume grew across the board.
Why is this important? Because growth driven by price increases has a ceiling. Customers will eventually switch to competitors or private labels. Volume-driven growth means people are actually buying more units.
Core EPS: $1.59, up 3% year over year
Growth across all 10 categories and 7 regions - no weak link
Beauty segment dragged results, grew 7% organically
The shaving and healthcare segments remained weak, with volume down 2%
King of dividends
If P&G has one thing it does better than almost anyone in the world, it's dividends. In April 2026, the company announced its 70th consecutive payout increase and raised its quarterly dividend to $1.0885, or $4.35 a year.
Seventy years without a break is extremely rare. Among the so-called dividend kings, of which there are five dozen, only five companies have reached that mark. Moreover, P&G has paid a dividend continuously for over 130 years. It has survived oil shocks, financial crises and pandemics.
For the full fiscal year 2026, the company plans to distribute about $15 billion to shareholders: about $10 billion in dividends and another $5 billion in share buybacks. At a share price of around $145, that works out to a dividend yield of around 3%. That's above average by P&G's standards, because a lower share price automatically raises the yield. But investors are cautious about the future, as is management.
"What do we know today about what the world will look like three months from now? I'm glad I don't have to give an outlook for next year today."
Andre Schulten, Procter & Gamble CFO
Boredom at a reasonable price
Not everything is rosy. Management warned that tariffs will cost the company about $400 million after taxes, and higher energy prices linked to tensions in the Middle East will add another $150 million or so. Management therefore expects full-year earnings to be more towards the lower end of the guidance range.
What is interesting, however, is where the stock is priced after last year's plunge. P&G is trading at around 21 times earnings, below its 10-year average of around 22.8 times. For a company of this quality, valuations have hit near five-year lows. Analysts at UBS are similarly bullish and have raised their price target to $172, which would give it decent upside room from current levels.
However, according to the fair price on Bulios, $PG stock is already above its intrinsic value.
The market tends to forget about defensive stocks when the euphoria around growth peaks, and only remembers them in moments of panic. P&G's price for 2026 is back about where it started, and today's jump of more than 4 percent is a reminder that all it takes is a whiff of uncertainty to turn capital back toward safety.