Komerční banka paid all profits to shareholders. And next year, probably also

Net profit of 18 billion, a record dividend and a P/E below 9. Why does the market still view one of the most profitable banks in Central Europe with suspicion?
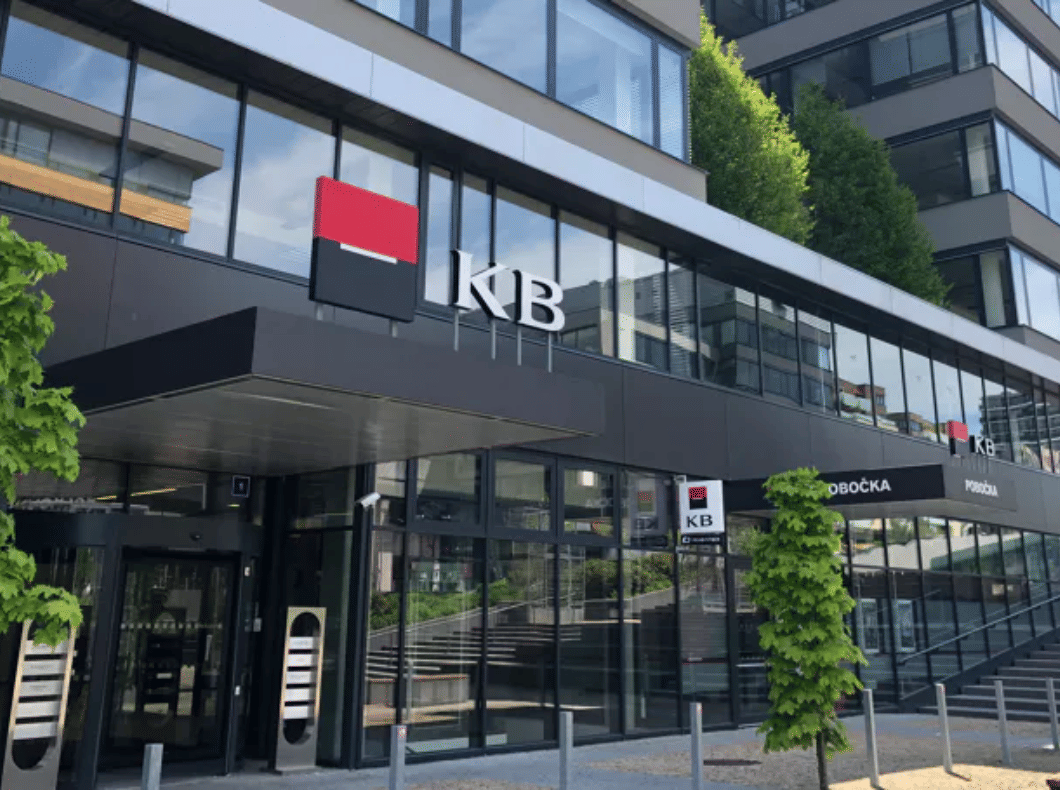
If Komerční banka $KOMB.PR were operating in the US or German market, its valuation would have long ago attracted the interest of institutional investors. A return on equity of over 14%, a 100% dividend payout ratio, a strong capital position - and yet the stock trades at a P/E of around 9. This is a fairly common picture on the Prague Stock Exchange. The question is whether it lasts too long.
A bank that makes money without any big surprises
For 2025, KB posted a net profit of CZK 18.06bn - 5% more than the year before. The result was mainly driven by a net dissolution of provisions and a significant reduction in operating expenses. Total sales for the year reached CZK 36.9 billion.
Although net interest income in the fourth quarter rose by only 0.5% compared to the previous quarter - below analysts' consensus - KB compensated for this with the excellent quality of its loan portfolio. The share of non-performing loans fell to 1.6%, while the volume of corporate loans increased significantly in the last quarter (+4.3% q-o-q).
The client base grew by 42,000 customers to 2.268 million. The volume of loans increased by 6.8% to CZK 905.8 billion, deposits by 5.8% to almost CZK 1.089 trillion.
"Komerční banka's operating results remained slightly below expectations in 2025. However, thanks to the release of provisions, the bank delivered 5% year-on-year growth in net profit to CZK 18.1bn. Management has previously announced that it will pay out all of last year's profit to shareholders."
Karel Nedved, analyst at Fio banka
For the third time in a row, all profits paid out
The April 2026 AGM approved a dividend of CZK 95.60 per share - 100% of net profit for 2025. The total payout amounted to CZK 18.1bn. The dividend was paid on 25 May 2026.
This is the third time in a row that KB has distributed all of its profits to shareholders. For 2024, it was CZK 91.30 per share, and for 2023 it was CZK 82.66. The dividend yield to share price is thus close to 8% gross - well above what Czech government bonds offer.
But the total generosity is probably not over. The outlook for 2026 assumes a payout ratio of 80% of net profit. Bloomberg analysts estimate the 2026 dividend at around CZK 72-76 per share - still attractive, just a bit more sober.
Capital above regulatory requirements, digitalisation complete
KB's capital adequacy ratio at the end of 2025 is 18.6%, while CET1's core capital is 17.7%. The regulatory minimum requirement lies well below that - giving KB a comfortable cushion that gives it room to manoeuvre both for dividends and potential acquisitions.
A significant milestone was reached in the area of digitisation: KB completed a massive migration of clients to the new KB+ platform in 2025, with the app crossing the 1.5 million active users milestone. According to management, this allowed the bank to slim down its operational structure and reduce costs. Bankers' capacities, which were tied up in the migration, are now being redirected to sales - i.e. mortgages and consumer loans, where the bank plans to gain market share more aggressively.
Key financial metrics for 2025:
Net profit: CZK 18.06 billion
Total revenue: CZK 36.9 billion
Loan volume: CZK 905.8 billion (+6.8%)
Customer deposits: CZK 1.089 trillion (+5.8%)
Capital adequacy ratio: 18.6%
Dividend: CZK 95.60 per share (100% of earnings)
P/E below 9 and 30% upside according to analysts - but beware of risks
The analyst consensus works with an average target price of around CZK 1,088, with a high of CZK 1,190. In current trading, this implies a potential of tens of percent. Meanwhile, the distribution of recommendations is quite clear: of the 13 houses surveyed, three recommend buying, nine hold, and none sell.
The P/E valuation of around 8-9 remains well below the average of comparable European banks, where similar institutions trade at multiples of 12-15. The question is why the gap persists.
Part of the answer lies in the risks the market assigns to regional exposure. Implementation of the Basel IV regulatory framework may increase capital requirements by 1.5-2 percentage points - this would make it difficult to maintain a 100% payout ratio. The CNB's lower base rate (currently 3.5%) is gradually squeezing net interest margins as banks need to offer more competitive terms to depositors. And then of course there are the fintechs - Revolut, Wise, etc. are consistently eroding margins in the payments segment, where the younger generation naturally gravitates to cheaper alternatives.
Three big banks, one oligopoly
KB together with ČSOB and Česká spořitelna hold over 70% of the Czech banking market. The majority owner - the French group Société Générale $GLE.PA with almost 60% of the shares - ensures a stable strategic background and access to international capital markets.
This market concentration has its advantages and disadvantages. On the one hand, it limits price competition and helps maintain healthy margins. On the other hand, regulators and the new MREL (minimum eligible liability requirements) rules increase funding costs, which in turn tightens margins.
KB is performing solidly in this environment. This is not a dramatic growth story, but rather a bank that is consistently earning, delivering on promises to shareholders, and waiting for the market to reassess higher.
Stocks mentioned